CM REGULATORY ALERT
Executive Summary
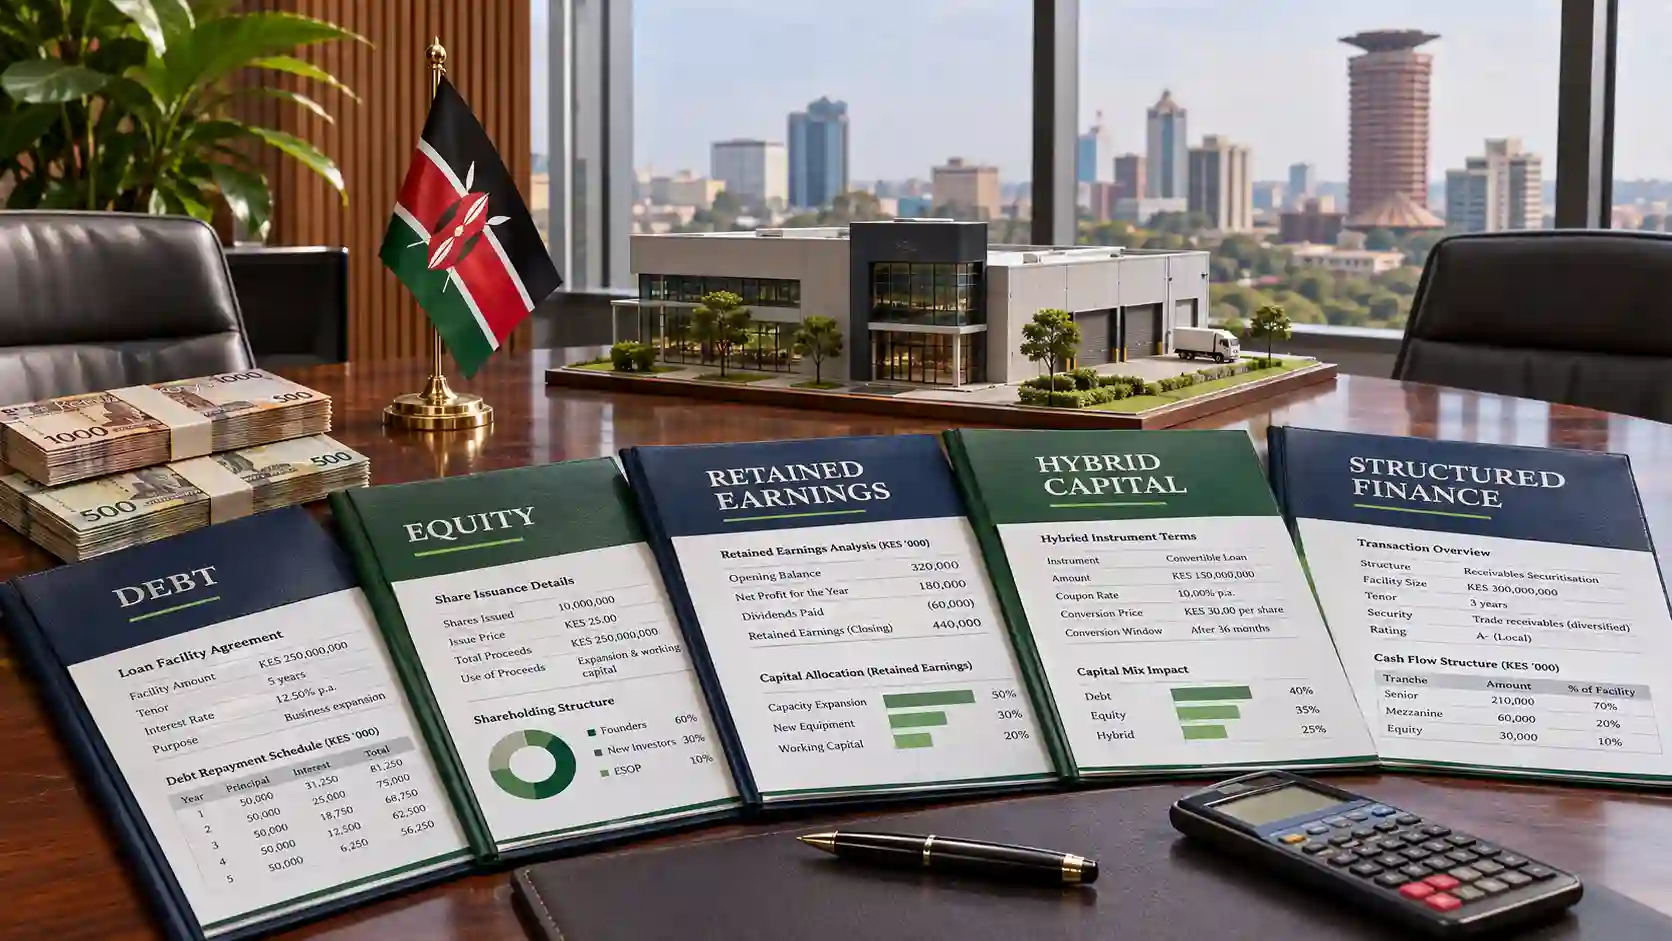
Access to appropriately structured capital is central to business formation, expansion, acquisitions, infrastructure development, working-capital management, refinancing and corporate restructuring. Kenyan companies generally finance their operations through three principal sources: debt funding, equity funding and internally generated capital.
In practice, the choice is rarely confined to a single source. A company may combine senior debt, shareholder loans, preference shares, mezzanine capital, convertible instruments, asset-backed facilities and retained earnings into a bespoke capital structure. This is commonly described as hybrid capital or structured finance.
The optimal funding structure depends on considerably more than the stated interest rate or valuation. A company and its board must assess its cash-flow capacity, repayment profile, security position, dilution, governance rights, tax treatment, foreign-exchange exposure, regulatory approvals, accounting -treatment, insolvency ranking and the investor’s intended exit.
Each source of capital presents distinct commercial, financial and legal implications.Debt ordinarily has to be repaid, usually carries interest, ranks ahead of equity on insolvency and is generally recognised as a liability. Equity represents ownership, generally has no fixed repayment date and absorbs greater enterprise risk, but may dilute existing shareholders’ economic and voting interests. Internal funding principally relies on retained earnings and avoids third-party financing obligations, although it may restrict growth or shareholder distributions. Hybrid capital combines selected features of debt and equity so that investor returns and company obligations can be aligned with the business’s cash flows, assets, risks and growth strategy.
A financing transaction should therefore begin with a disciplined assessment of what the company requires, when it requires it, how the capital will be serviced or returned, and which risks should be retained by the company or transferred to financiers and investors.
-
The Corporate Funding Framework
Companies require capital at different stages of their lifecycle. A start-up may depend primarily on equity because it has limited assets, an uncertain revenue profile and insufficient cash flow to service conventional debt. A mature company with predictable revenues may be able to borrow against its balance sheet or cash flows. A property developer may require construction finance supported by land, presales, receivables and controlled project accounts. An infrastructure project may need long-tenor debt combined with sponsor equity, guarantees, revenue assignments and carefully structured security arrangements.
The appropriate structure must be aligned with the purpose and amount of the funding, the timing and certainty of repayment, projected cash flows, available security, promoters’ willingness to dilute ownership, the investor’s required return and exit, applicable regulation, tax and accounting consequences, and the company’s capacity to comply with financial and operational covenants.
The principal characteristics may be summarised as follows:
|
Issue |
Debt funding |
Equity funding |
Internal funding |
|
Nature |
Borrowed capital |
Ownership capital |
Accumulated business profits |
|
Investor return |
Interest, fees and possible participation rights |
Dividends and capital appreciation |
Return generated through reinvestment |
|
Repayment |
Contractually repayable |
Generally no fixed repayment date |
No external repayment obligation |
|
Balance-sheet treatment |
Generally recorded as a liability |
Generally recorded as shareholders’ equity |
Reflected within retained earnings |
|
Control |
Covenants, information and enforcement rights |
Voting, governance and reserved-matter rights |
Existing ownership ordinarily preserved |
|
Security |
May be secured or unsecured |
Ordinarily unsecured |
Not applicable |
|
Insolvency ranking |
Generally ranks ahead of equity |
Subordinated to creditors |
Forms part of shareholders’ funds |
|
Tax treatment |
Interest may be deductible subject to applicable limitations |
Dividends are generally distributions rather than deductible expenses |
Profits are retained after company-level taxation |
|
Principal risk |
Debt-service pressure and enforcement |
Dilution and investor influence |
Reduced liquidity and shareholder distributions |
The accounting treatment of any instrument ultimately depends on its substance and contractual terms under the applicable financial-reporting standards. A financing instrument described commercially as “equity” may still be treated as a financial liability where its terms impose an unavoidable repayment or redemption obligation.
-
Debt Funding
Debt is capital received by a company subject to an obligation to repay the principal, ordinarily together with interest, fees and other financing costs. It may take the form of bank loans, overdrafts, revolving facilities, trade and supplier finance, shareholder loans, syndicated lending, private credit, corporate bonds, notes and debentures, asset finance, leasing, receivables finance, acquisition finance, real estate finance, project finance, export finance or asset-backed funding.
Debt enables promoters to raise capital without immediately surrendering ownership. It may also be structured around the company’s business cycle through grace periods, revolving limits, amortisation schedules, bullet repayments, cash sweeps and seasonal repayment arrangements. Where structured appropriately, debt may be less dilutive than equity and provide an efficient means of financing assets or activities capable of generating predictable cash flows.
Debt also introduces fixed or ascertainable payment obligations irrespective of whether the company makes a profit. Excessive leverage can impair liquidity, expose the business to interest-rate or foreign-exchange volatility, restrict dividends and further borrowing, trigger defaults through covenant breaches and result in enforcement against secured assets. Boards should therefore stress-test proposed facilities against delays, cost overruns, reduced revenues, currency movements, higher interest rates and other downside scenarios.
Interest and qualifying financing costs may be deductible in determining taxable income. Deductibility is nevertheless subject to the Income Tax Act, transfer-pricing principles, applicable interest-limitation rules and the requirement that the expenditure be incurred in producing taxable income.
Cross-border debt may also attract withholding tax, treaty and permanent-establishment considerations. The applicable treatment depends on the character of the payment, the residence and status of the financier and the terms of the relevant double-taxation agreement.
2.1 Security and perfection
Debt may be secured through charges over land, debentures, fixed and floating charges, assignments of receivables, share charges, account charges, guarantees, insurance assignments and security over movable assets.
Security does not become fully effective merely because it is included in a facility agreement. It must be executed, stamped, registrered , notificated and and perfected within the relevant statutory periods. Depending on the nature of the transaction and the secured assets, registration may be required at the Companies Registry, Lands Registry and Movable Property Security Rights Registry (the Collateral Regisrty).
Financiers should carry out due diligence on ownership, title, corporate authority, existing encumbrances, competing claims, contractual restrictions, priority and the enforceability of the proposed security package. Borrowers should, in turn, examine whether the security is proportionate and whether the documents permit substitutions, releases and dealings with assets in the ordinary course of business.
2.2 Private credit
Private credit has become an increasingly important alternative where conventional bank lending may be unavailable, insufficiently flexible or unable to match the speed and risk profile of a transaction. Private lenders may provide tailored capital against cash flows, receivables, shares, projects or specific assets.
Such flexibility may be accompanied by enhanced pricing, stricter information rights, equity participation, warrants, step-in rights or tighter default protections. Companies should therefore evaluate the total economic cost of the financing rather than the interest rate alone.
Regulatory analysis is also essential to determine whether the financier’s activities require licensing or could amount to regulated credit provision, deposit-taking, collective investment activity or another regulated financial service.
Kenya -has now operationalized a comprehensive licensing and supervisory framework for non-deposit-taking credit providers following the gazetting of the Central Bank of Kenya (Non-Deposit Taking Credit Providers) Regulations, 2026 (Legal Notice No. 191 of 2026. Regulatory perimeter analysis is therefore important for private-credit funds, family offices, investment vehicles, fintech lenders and other non-bank providers of corporate credit.
-
Equity Funding
Equity funding involves issuing ownership interests to existing or new investors. Unlike conventional debt, ordinary equity does not ordinarily require repayment on a fixed date. The investor’s return depends primarily on dividends, capital appreciation and the proceeds realised upon an exit.
Equity may be raised through founder contributions, rights issues, private placements, angel investment, venture capital, private equity, strategic investment, institutional investment, public offerings, employee share-ownership arrangements or further investment by existing shareholders.
3.1 Ordinary shares
Ordinary shares commonly confer voting rights, rights to dividends when lawfully declared and participation in residual assets after creditors and senior investors have been satisfied.
The commercial terms of an equity investment should be documented through the company’s constitutional documents and a comprehensive shareholders’ or investment agreement. These documents should address board representation, voting thresholds, reserved matters, information rights, pre-emption rights, anti-dilution protection, restrictions on share transfers, tag-along and drag-along rights, founder vesting, deadlock resolution, dividend policy, investor exits and dispute-resolution mechanisms.
3.2 Preference shares
Preference shares can provide priority over ordinary shares in relation to dividends, capital repayment or both. They may be cumulative or non-cumulative, redeemable or non-redeemable, participating or non-participating, voting or non-voting, and convertible or non-convertible.
Although preference shares may be described commercially as equity, their accounting, tax and insolvency treatment depends on their substantive terms. A mandatory redemption obligation or an unavoidable fixed payment may cause an instrument to exhibit debt-like characteristics.
3.3 Advantages and disadvantages of equity
Equity can provides companies with patient capital without conventional amortisation pressure. It may strengthen the company’s balance sheet, improve borrowing capacity and introduce stronger institutional governance. A strategic and institutional investor may also provide industry expertise, technology, new markets access and commercial relationships and improved corporate governance.
The principal trade-off is dilution. Existing shareholders may surrender a percentage of future profits, voting power and sale proceeds. Minority-protection provisions, investor vetoes and reserved matters may also restrict promoters’ freedom to manage, finance or restructure the company.
Dividends are distributions of profits rather than deductible operating expenses. They may only be declared and paid in accordance with the Companies Act, the company’s constitution and applicable requirements concerning distributable profits and and, for public companies, the applicable net-asset restrictions.
-
Public and Private Offers of Securities
A company raising capital through shares, bonds, notes or other securities must determine at an early stage whether the transaction constitutes a public offer, private offer or another regulated securities transaction. A private company limited by shares may not offer its securities to the public under the Companies Act .
Public offers, listings, private offers, disclosure documents, fixed-income securities and continuing issuer obligations are goverened by The Capital Markets Act and the Capital Markets (Public Offers, Listings and Disclosures) Regulations, 2023. The Regulations contain a dedicated framework for private offers and distinguish them from public fundraising.
A purported private placement should not be marketed indiscriminately say through social media, mass advertising or unrestricted public solicitation may be treated as a public offerand it it therefore imperative that its structure, investor universe, communications, information memorandum and allotment process must be reviewed against the applicable regulatory criteria .
Where the transaction falls within the public-offer framework, the issuer would require approval from the Capital Markets Authority, prescribed disclosure documentation, professional advisers, corporate-governance arrangements and compliance with listing or continuing-obligation requirements.
In any case the regulatory analysis should be undertaken before prospective investors are approached or commitments accepted. An incorrectly marketed “private” offer may expose the issuer, its directors, promoters and advisers to significant regulatory and enforcement risk.
-
Internal Funding and Retained Earnings
Internal funding arises where a company reinvests profits accumulated from its operations instead of distributing them to shareholders. Retained earnings allow a business to finance expansion without external interest, financing fees, dilution, security or third-party covenants. They can also preserve borrowing capacity for future requirements.
Internal funding is nevertheless not cost-free. Capital reinvested in the business could otherwise have been distributed to shareholders or deployed in a higher-return opportunity. Excessive retention may also cause shareholder disputes, particularly where minority shareholders expect dividends while controlling shareholders prefer continued reinvestment.
The board should adopt a defensible capital-allocation and dividend policy that balances operational liquidity, maintenance expenditure, expansion requirements, debt servicing, contingency reserves, shareholder distributions and the company’s long-term strategy.
Retained earnings are generally reflected within shareholders’ equity on the balance sheet. Unlike interest, dividends are distributions rather than expenses recognised in determining the company’s operating profit.
-
Hybrid Capital: Bridging Debt and Equity
Hybrid capital combines selected characteristics of debt and equity. It is particularly useful where a company requires flexible or patient capital, but investors require downside protection, a priority return or participation in future enterprise growth.
-
A convertible loan or note begins as debt but may convert into shares following an agreed event, such as a qualified financing, maturity, default, investor election or sale of the company. Its terms should clearly address the conversion price, valuation cap, discount, accrued interest, maturity, conversion triggers, investor protections and treatment upon an exit.
-
Mezzanine finance ordinarily ranks behind senior lenders but ahead of ordinary equity. Its return may combine interest, fees, warrants, profit participation or an equity-conversion feature. It can bridge the funding gap where senior lenders are unwilling to provide the entire capital requirement and promoters wish to avoid immediate or excessive dilution.
-
Participating or redeemable preference shares may provide a preferred dividend or redemption return together with participation in additional profits or disposal proceeds. Their terms can be adapted to match investor return expectations while preserving agreed governance rights.
-
Shareholder loans allow promoters or investors to inject part of their capital as equity and part as debt. They may provide repayment flexibility, but their terms must be properly documented and commercially supportable. Related-party and cross-border loans require particular attention to transfer pricing, withholding tax, interest deductibility, foreign-exchange exposure and subordination to senior lenders.
-
Under revenue-based or profit-participating finance, the financier’s return is calculated by reference to revenue, profits, production, sales or cash collections rather than conventional fixed interest. The documentation must clearly address applicable accounting principles, information and audit rights, payment caps, manipulation risk and treatment where the company underperforms.
-
Payment-in-kind instruments allow interest or preferred returns to accrue or be capitalised rather than paid periodically in cash. This can preserve early-stage liquidity but may substantially increase the company’s leverage and maturity obligations over time.
-
Structured Finance
Structured finance goes beyond selecting a particular instrument. It uses contractual, corporate, security and cash-flow arrangements to allocate risks and make an otherwise difficult transaction financeable.
A structured transaction may involve a special-purpose vehicle, ring-fenced project assets and liabilities, escrow or controlled collection accounts, assignments of receivables, payment waterfalls, reserve accounts, guarantees, credit enhancement, security trustees, intercreditor arrangements, hedging, completion support, insurance assignments, direct agreements and lender step-in rights.
Structured finance is particularly relevant to real estate, energy, infrastructure, telecommunications, manufacturing, agriculture, healthcare, hospitality, education, transport and asset-backed transactions.
The objective is not merely to create a larger suite of transaction documents. It is to identify the transaction’s principal risks and allocate each risk to the party best able to control, absorb, mitigate or price it.
-
Key Legal, Regulatory and Tax Considerations
-
The company must first confirm that the proposed financing and security are permitted by its constitution and have received the necessary board, shareholder or class approvals. Directors must exercise independent judgment, act for a proper purpose, disclose conflicts and consider the company’s present and prospective financial position.
-
An issue or offer of shares, bonds, notes or investment interests may require CMA approval or compliance with the private-offer framework. The pooling of capital from multiple investors may also raise collective-investment, alternative-investment-fund or intermediary-licensing questions.
-
Depending on the applicable sectoral regime, banks, insurers, telecommunications operators, energy companies, pension-related entities and other regulated businesses may require prior approval for significant borrowing, security creation, new investors or changes in control.
-
An equity investment, joint venture or conversion of debt into shares may constitute a merger or acquisition of control requiring notification to and in some cases approval by, the Competition Authority of Kenya or a regional competition authority, subject to the applicable jurisdictional thresholds and exemptions. Sector-specific foreign-ownership limitations must also be examined.
-
Tax analysis should address interest deductibility, withholding tax, transfer pricing, arrangement and guarantee fees, stamp duty, capital gains tax, VAT, conversion or redemption, treaty relief and permanent-establishment exposure. The tax characterisation of an instrument may differ from its commercial label.
-
Foreign-currency borrowing may offer a lower nominal interest rate but expose the company to significant currency risk. The company should consider natural hedges, currency-matched revenues, derivatives and agreed conversion or adjustment mechanisms.
-
The parties must also determine how the financing will rank upon enforcement or insolvency. Transaction documents should clearly address seniority, subordination, payment blockage, enforcement standstill, turnover obligations and distribution waterfalls.
-
Selecting the Appropriate Funding Structure
No single source of capital is universally preferable. A company should determine whether the funding is intended for working capital, capital expenditure, acquisition, refinancing or a long-term project; whether cash flows can service fixed debt; what security is available; whether the promoters are willing to dilute ownership; and what return and exit the financier expects.
It should also consider whether the funding currency matches its revenues, what happens if completion or sales are delayed, whether existing lenders have imposed negative pledges or consent requirements, how the instrument will be treated for tax and accounting purposes, and whether the company can refinance, redeem or prepay it without punitive cost.
A growing company will frequently benefit from a properly designed capital stack rather than a single source of funding. This may comprise sponsor equity, retained earnings, senior secured debt, mezzanine capital and investor preference shares, with each layer performing a distinct risk-allocation and return function.
-
Recommended Actions for Boards and Promoters
Before commencing a capital raise, companies should prepare an integrated financial model and funding plan, determine the appropriate combination of debt, equity and hybrid capital, and conduct corporate, legal, tax and regulatory due diligence.
The company should establish a secure investor data room, negotiate a comprehensive term sheet before incurring extensive documentation costs, and assess the transaction’s effect on control, dilution and future fundraising. It should map all required corporate and regulatory approvals, negotiate covenants against realistic downside scenarios, identify and perfect the security package, document shareholder and intercreditor arrangements, and implement escrow, controlled-account or cash-waterfall protections where appropriate.
The financing should also be tested against the company’s broader strategic plan. Capital that solves an immediate liquidity problem but creates unsustainable repayment obligations, loss of control or future refinancing risk may ultimately be substantially more expensive than its stated pricing suggests.
-
How We Can Assist
Through our Hybrid Capital & Structured Finance Practice, CM Advocates LLP advises companies, founders, investors, lenders, private-credit providers, family offices, development-finance institutions and project sponsors on the design, negotiation, implementation, refinancing and restructuring of sophisticated funding arrangements.
Our work includes funding-readiness and capital-structure reviews; debt, equity and hybrid-finance structuring; private placements and capital-markets compliance; venture-capital and private-equity transactions; shareholder and preference-share financing; convertible notes and mezzanine capital; corporate bonds, notes and debentures; acquisition and leveraged finance; project, infrastructure and real estate finance; asset-backed and receivables financing; private credit and cross-border facilities; security structuring, registration and perfection; escrow and controlled-account arrangements; intercreditor, priority and subordination agreements; financial restructuring and distressed financing; regulatory approvals; transaction tax structuring; and legal opinions on capacity, enforceability, security and regulatory compliance.
Our multidisciplinary approach draws upon our Corporate & Commercial, Banking & Finance, Capital Markets, Tax, Real Estate, Projects, Insolvency and Dispute Resolution teams to provide integrated support throughout the financing lifecycle.
Contact Us
Hybrid Capital & Structured Finance (HCSF) Practice
E: hcsfpractice@cmadvocates.com
Tax & International Business Advisory (TIBA) Unit
E: taxadvisory@cmadvocates.com
CM Advocates LLP
Head Office – Nairobi
I&M Bank House, 7th Floor
2nd Ngong Avenue
Nairobi.
Mombasa Office
Links Plaza, 3rd Floor
Links Road, Nyali
Mombasa.
E: mombasaoffice@cmadvocates.com
Regional Presence
Kenya | Uganda | Tanzania | Rwanda | Zambia | Ethiopia | South Sudan
Disclaimer: This Regulatory Alert is provided for general information only and does not constitute legal, tax, accounting, investment or financial advice. Appropriate professional advice should be obtained before any action is taken or transaction is implemented.